News Analysis: Indian Railways’ New Cement Freight Policy – A Structural Shift for the Sector

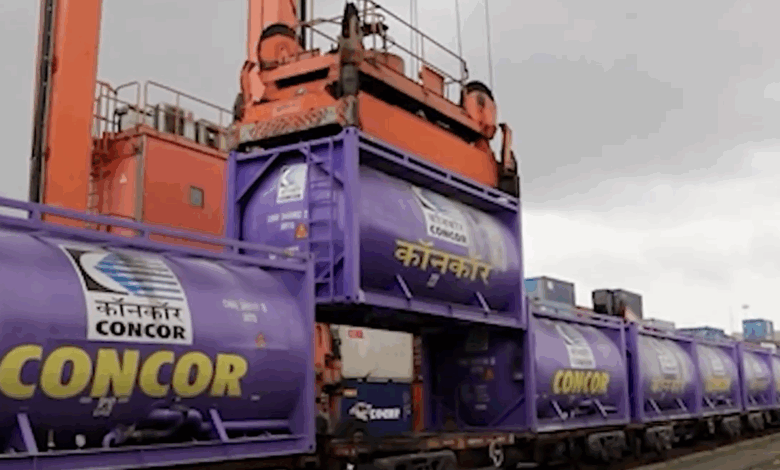
Indian Railways has introduced one of the most significant freight reforms in recent years with a flat ₹0.90 per tonne-km rate for bulk cement moved in tank containers and a dedicated Bulk Cement Terminal policy under PPP mode. The policy removes the old distance- and weight-slab structure that made rail unviable for hauls below 300–350 km.
Rate Comparison: Old vs New (Bulk Cement)
| Distance | Old Effective Rate (avg.) | New Rate | Savings % |
| 0–200 km | ₹1.25–1.45 /tonne-km | ₹0.90 | 30–38% |
| 200–400 km | ₹1.05–1.20 /tonne-km | ₹0.90 | 20–25% |
| >400 km | ₹0.95–1.05 /tonne-km | ₹0.90 | 5–10% |
| All-India Weighted Average Savings | — | — | ~30% (official estimate) |
Road freight benchmark: ₹1.60–2.20 /tonne-km.
Post-policy, rail is now 45–60% cheaper than road even at 150–200 km.
Impact on Railways’ Freight Revenue
- Current cement contribution: ~₹10,000–12,000 crore annually (8% of total freight revenue)
- Present rail share: 8–9% (87 MT bagged + 7 MT bulk)
- Target: Triple bulk volumes from 7 MT to 21–25 MT in 3–4 years
- Expected outcome: Lower rate offset by 3× volume → net additional revenue of ₹12,000–18,000 crore per year by FY29
Company-wise Benefit Matrix (FY26–FY28 annualized savings)
| Company | Capacity (MTPA) | Avg Lead (km) | Est. Annual Logistics Savings | EBITDA Margin Gain | Key Advantage |
| UltraTech Cement | 148 | 380 | ₹380–520 crore | +220–300 bps | Highest absolute spend |
| Ambuja + ACC (Adani) | 82 | 420 | ₹260–360 crore | +180–250 bps | Early tank container pilots; East/N-E strength |
| Shree Cement | 56 | 350 | ₹140–190 crore | +200–280 bps | High bulk readiness |
| Dalmia Bharat | 46 | 480 | ₹110–150 crore | +250–320 bps | Longest lead distance; sharp rail volume growth in East |
| JK Lakshmi Cement | 20 | 280 | ₹55–80 crore | +300–400 bps | Rail now viable for short leads |
| Ramco Cements | 24 | 320 | ₹60–90 crore | +220–300 bps | South-focused; upcoming terminals in TN/AP |
| Others (mid-size/regional) | ~200 combined | 250–400 | ₹600–900 crore (aggregate) | +100–200 bps | Collective benefit for 40+ players |
Total sector-level savings: ₹1,800–2,400 crore per year once rail share reaches 25–30% (expected by FY28).
Strategic Winners
- Adani Group (Ambuja + ACC): Already running pilot rakes; fastest execution capability
- UltraTech: Scale to absorb container capex and secure terminals
- Eastern/N-E players (Dalmia, Shree, Star Cement): Region already seeing 71% YoY rail loading growth
- Pure bulk players (Shree, Nuvoco): No bagging cost disadvantage
Key Execution Risks
- Availability of ISO tank containers (current fleet <2,000; need 15,000+ in 3 years)
- Pace of Bulk Cement Terminal rollout (first 10–15 terminals critical)
- Container leasing economics and return-load availability
This policy marks the biggest structural cost-saving trigger for the Indian cement industry since GST, fundamentally altering modal economics in favor of large, integrated players with pan-India networks and bulk-handling infrastructure.